
Written by Gurjit Ghai, REALTOR®
Rexara Realty Inc.·Published: September 12, 2026·Financing
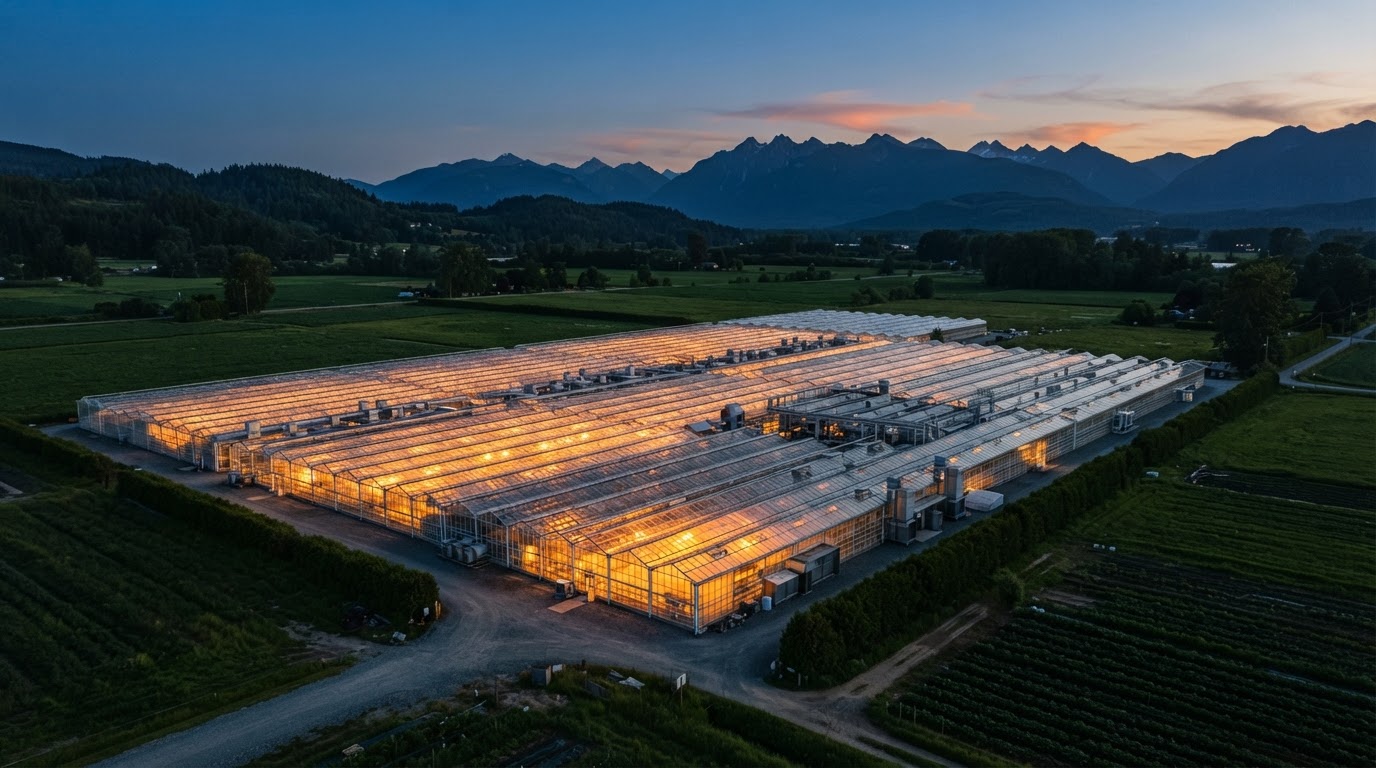
Financing farmland is fundamentally different from financing a residential home. Lenders assess not just the borrower and the buildings, but the land itself — its soil capability, water, income potential, and whether it is in the Agricultural Land Reserve. A working farm is valued partly as real estate and partly as a productive asset, and that changes how a loan is underwritten.
In Canada, agricultural lending often involves specialist lenders. Farm Credit Canada (FCC) is a federal Crown corporation that lends specifically to the agriculture sector, and chartered banks also have agribusiness divisions. Down payments, amortisation periods and the documentation required can differ from a standard residential mortgage, and lenders may look at the farm's projected or actual income to support the loan.
For buyers, preparation matters. Expect to provide more documentation than a home purchase — potentially a farm business plan, financial statements, and information about quotas, water licences, equipment and existing leases. If the property includes a residence, the financing structure may separate the home from the farm portion. ALR land can also affect what a lender will finance and on what terms.
If you are financing a farm purchase, speak to a lender who understands agricultural property early in the process — not after you have made an offer. Read our Financing a Farm guide for more, and treat this as educational information rather than financial advice.
Gurjit Ghai, REALTOR®
Personal Real Estate Corporation
Brokerage: Rexara Realty Inc.
Gurjit Ghai is a BC real estate professional specializing in agricultural land, ALR properties, and farm operations across British Columbia. He helps buyers and sellers navigate water rights, soil capability, farm classification, and the unique due diligence that farmland transactions require.